

Más información sobre el libro
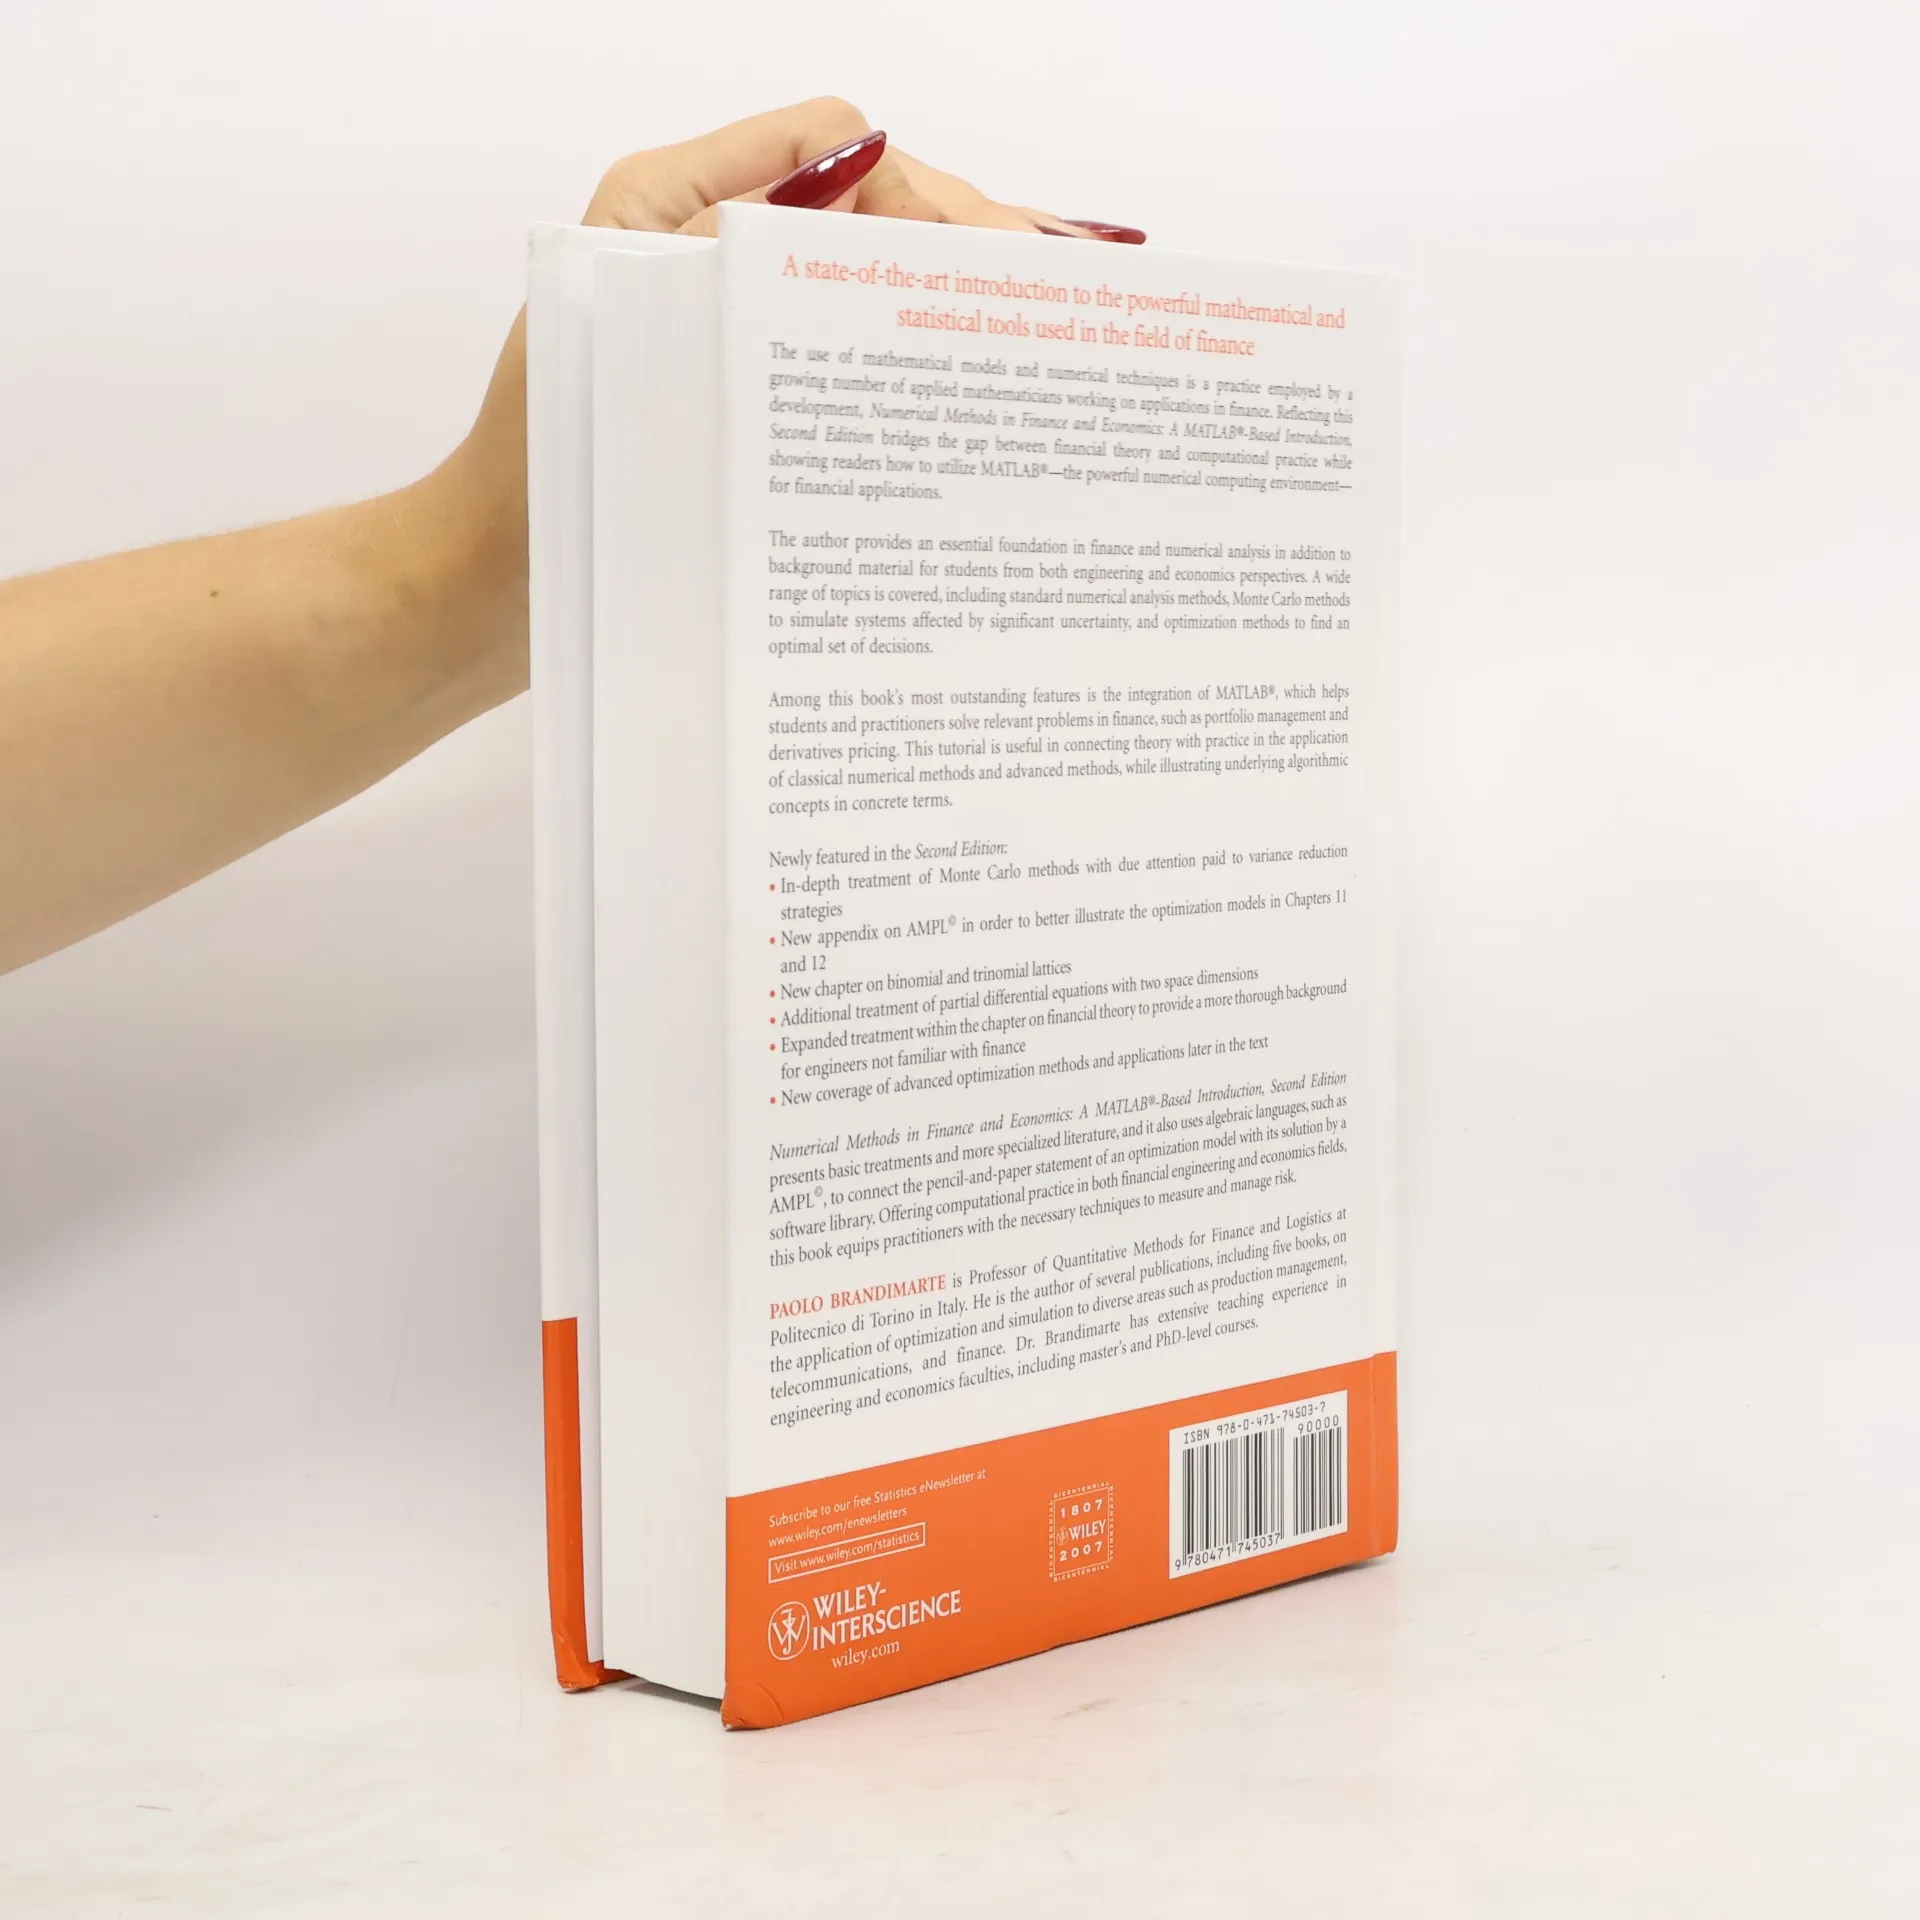
This book serves as a comprehensive introduction to the mathematical and statistical tools essential in finance, reflecting the increasing use of mathematical models by applied mathematicians in this field. It bridges the gap between financial theory and computational practice, demonstrating how to utilize MATLAB, a powerful numerical computing environment, for various financial applications. The author lays a solid foundation in finance and numerical analysis, catering to students from engineering and economics backgrounds. Key topics include standard numerical analysis methods, Monte Carlo methods for simulating uncertain systems, and optimization techniques for decision-making. Notable features include an in-depth exploration of Monte Carlo methods with a focus on variance reduction, an appendix on AMPL to illustrate optimization models, and a new chapter on binomial and trinomial lattices. The treatment of partial differential equations is expanded, and there is enhanced coverage of financial theory to better support engineers unfamiliar with finance. Additionally, advanced optimization methods and applications are introduced later in the text. This book combines basic treatments with specialized literature, using algebraic languages like AMPL to connect optimization models with software solutions. It equips practitioners in financial engineering and economics with vital techniques for measuring and managing risk.
Compra de libros
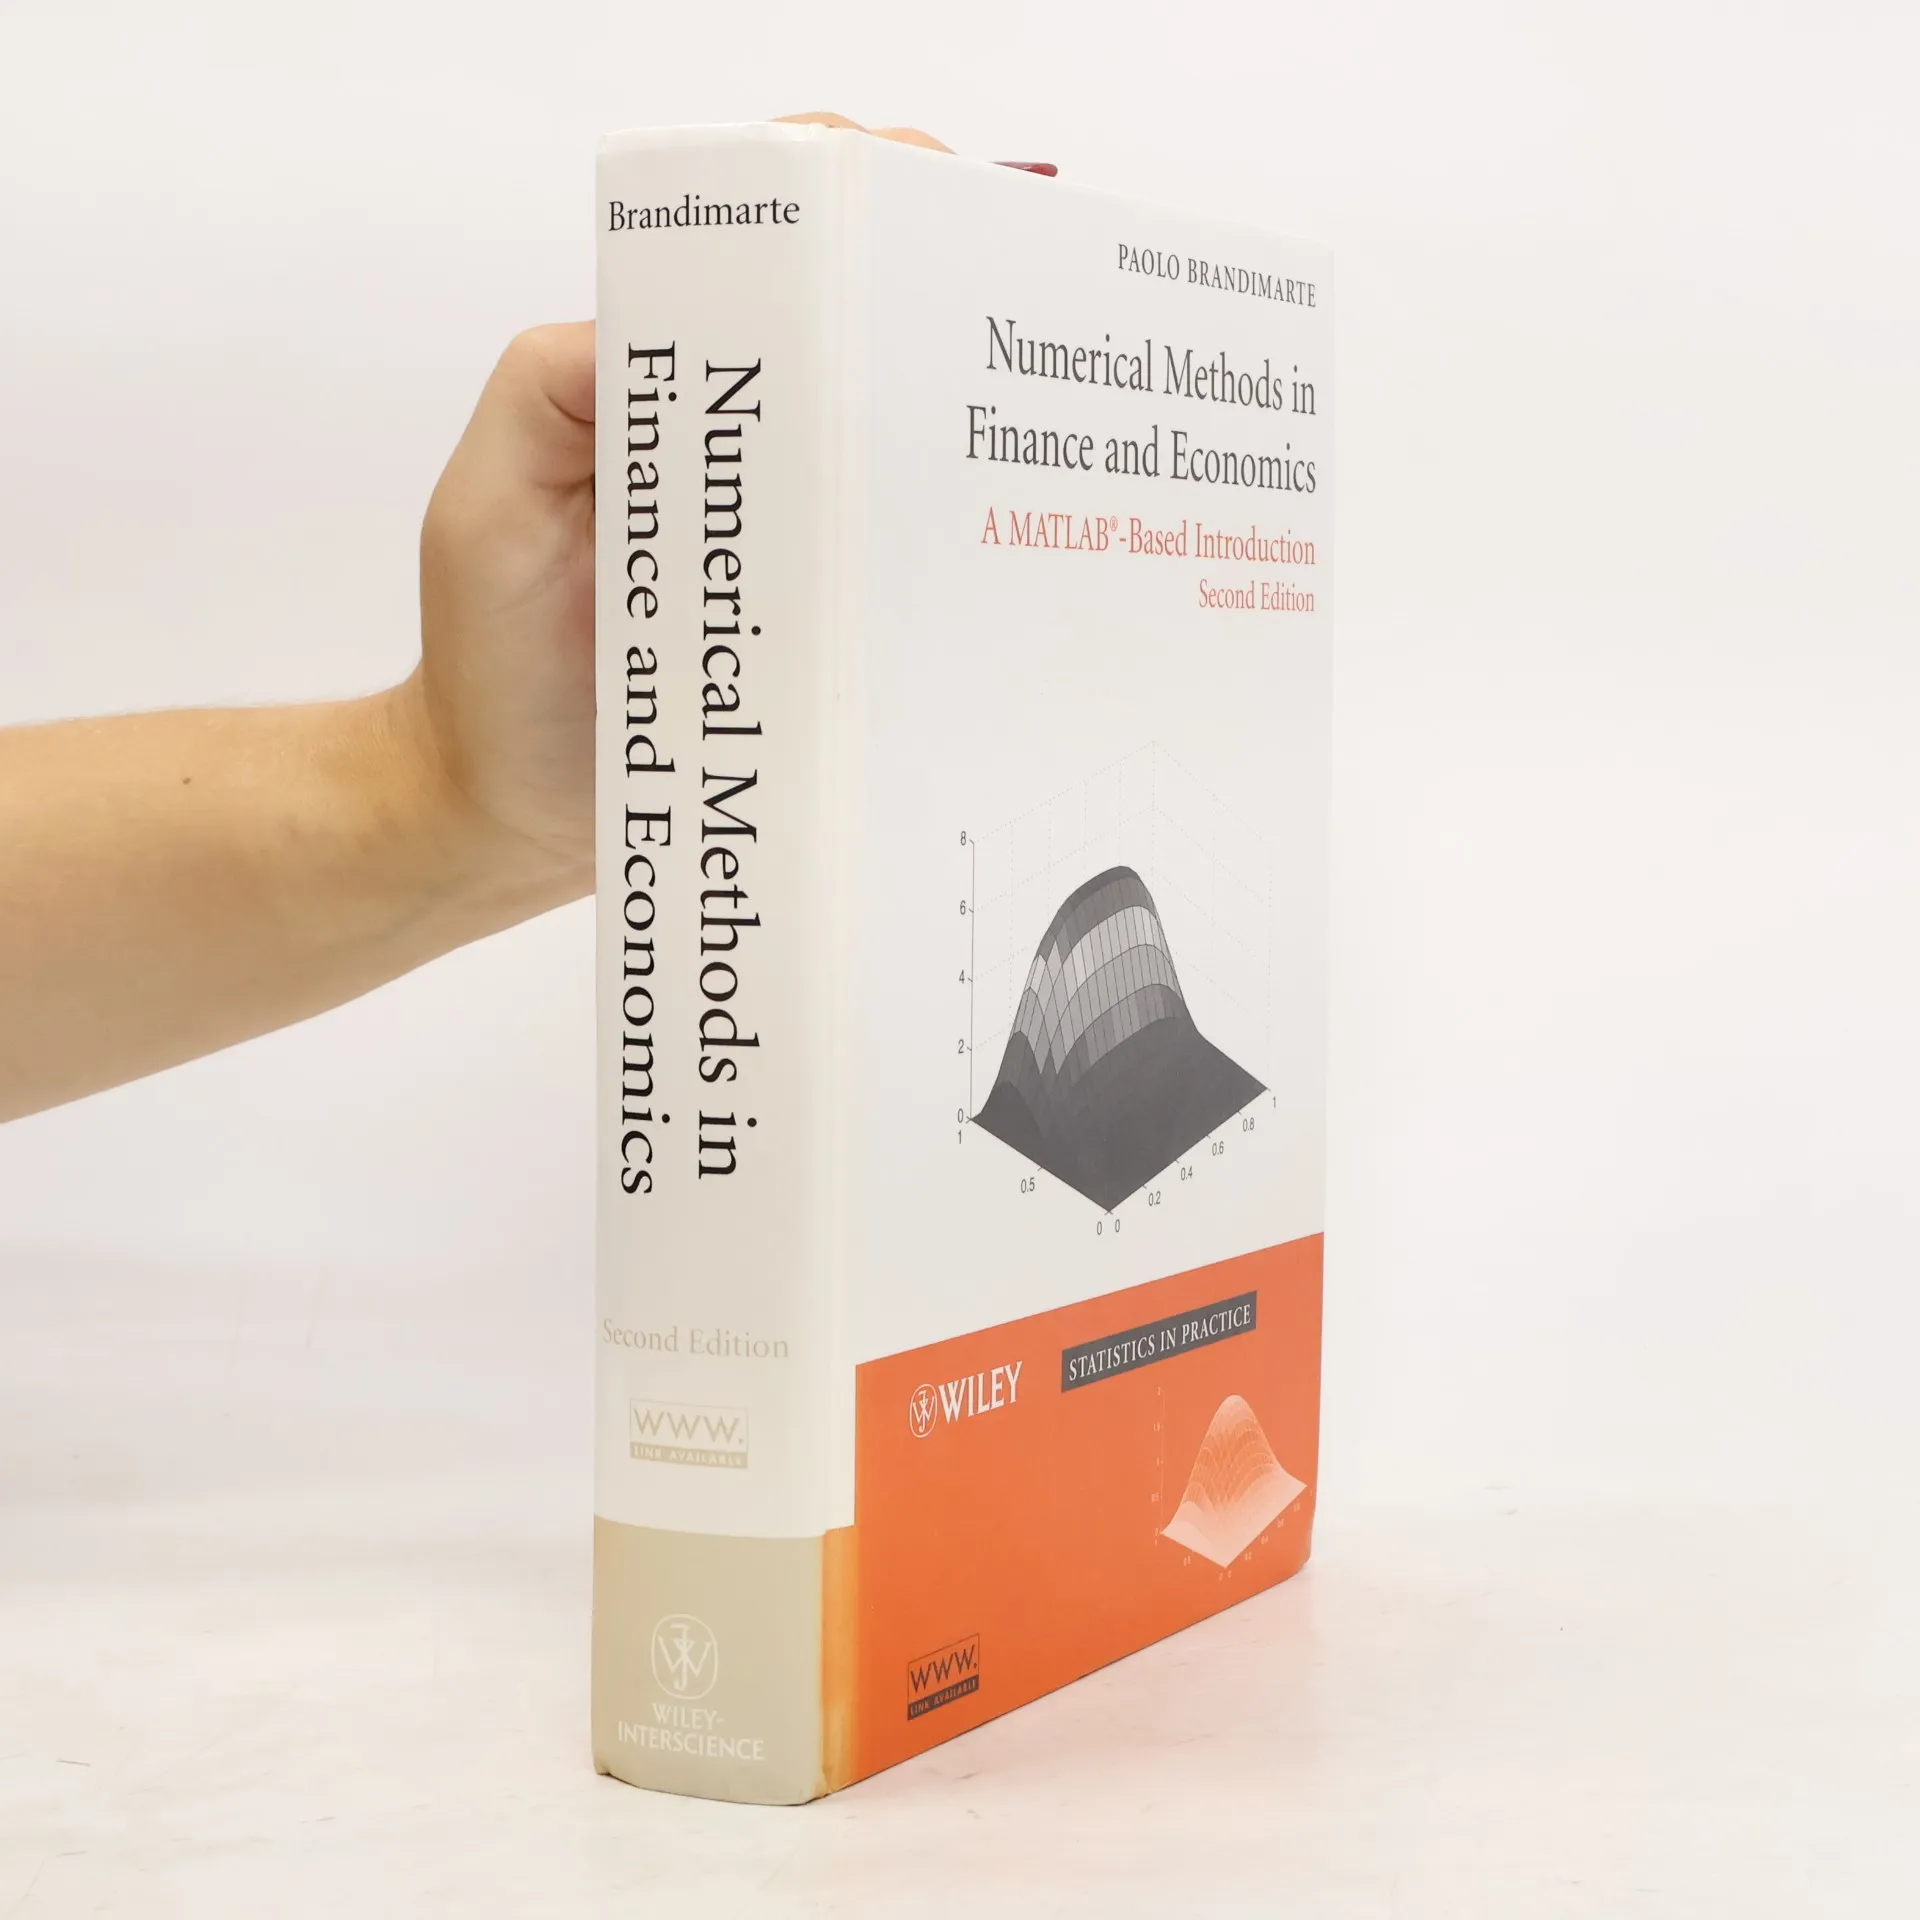
Statistics in Practice: Numerical Methods in Finance and Economics, Paolo Brandimarte
- Idioma

- Publicado en
- 2006
- Encuadernación
- (Tapa dura)
Métodos de pago
Nadie lo ha calificado todavía.
- Título
- Statistics in Practice: Numerical Methods in Finance and Economics
- Subtítulo
- A MATLAB-Based Introduction - Second Edition
- Idioma
- Inglés
- Autores
- Paolo Brandimarte
- Editorial
- Wiley-Interscience
- Publicado en
- 2006
- Formato
- Tapa dura
- Páginas
- 696
- ISBN10
- 0471745030
- ISBN13
- 9780471745037
- Serie
- Categorías
- Descripción
- This book serves as a comprehensive introduction to the mathematical and statistical tools essential in finance, reflecting the increasing use of mathematical models by applied mathematicians in this field. It bridges the gap between financial theory and computational practice, demonstrating how to utilize MATLAB, a powerful numerical computing environment, for various financial applications. The author lays a solid foundation in finance and numerical analysis, catering to students from engineering and economics backgrounds. Key topics include standard numerical analysis methods, Monte Carlo methods for simulating uncertain systems, and optimization techniques for decision-making. Notable features include an in-depth exploration of Monte Carlo methods with a focus on variance reduction, an appendix on AMPL to illustrate optimization models, and a new chapter on binomial and trinomial lattices. The treatment of partial differential equations is expanded, and there is enhanced coverage of financial theory to better support engineers unfamiliar with finance. Additionally, advanced optimization methods and applications are introduced later in the text. This book combines basic treatments with specialized literature, using algebraic languages like AMPL to connect optimization models with software solutions. It equips practitioners in financial engineering and economics with vital techniques for measuring and managing risk.