



Parámetros
- 756 páginas
- 27 horas de lectura
Más información sobre el libro
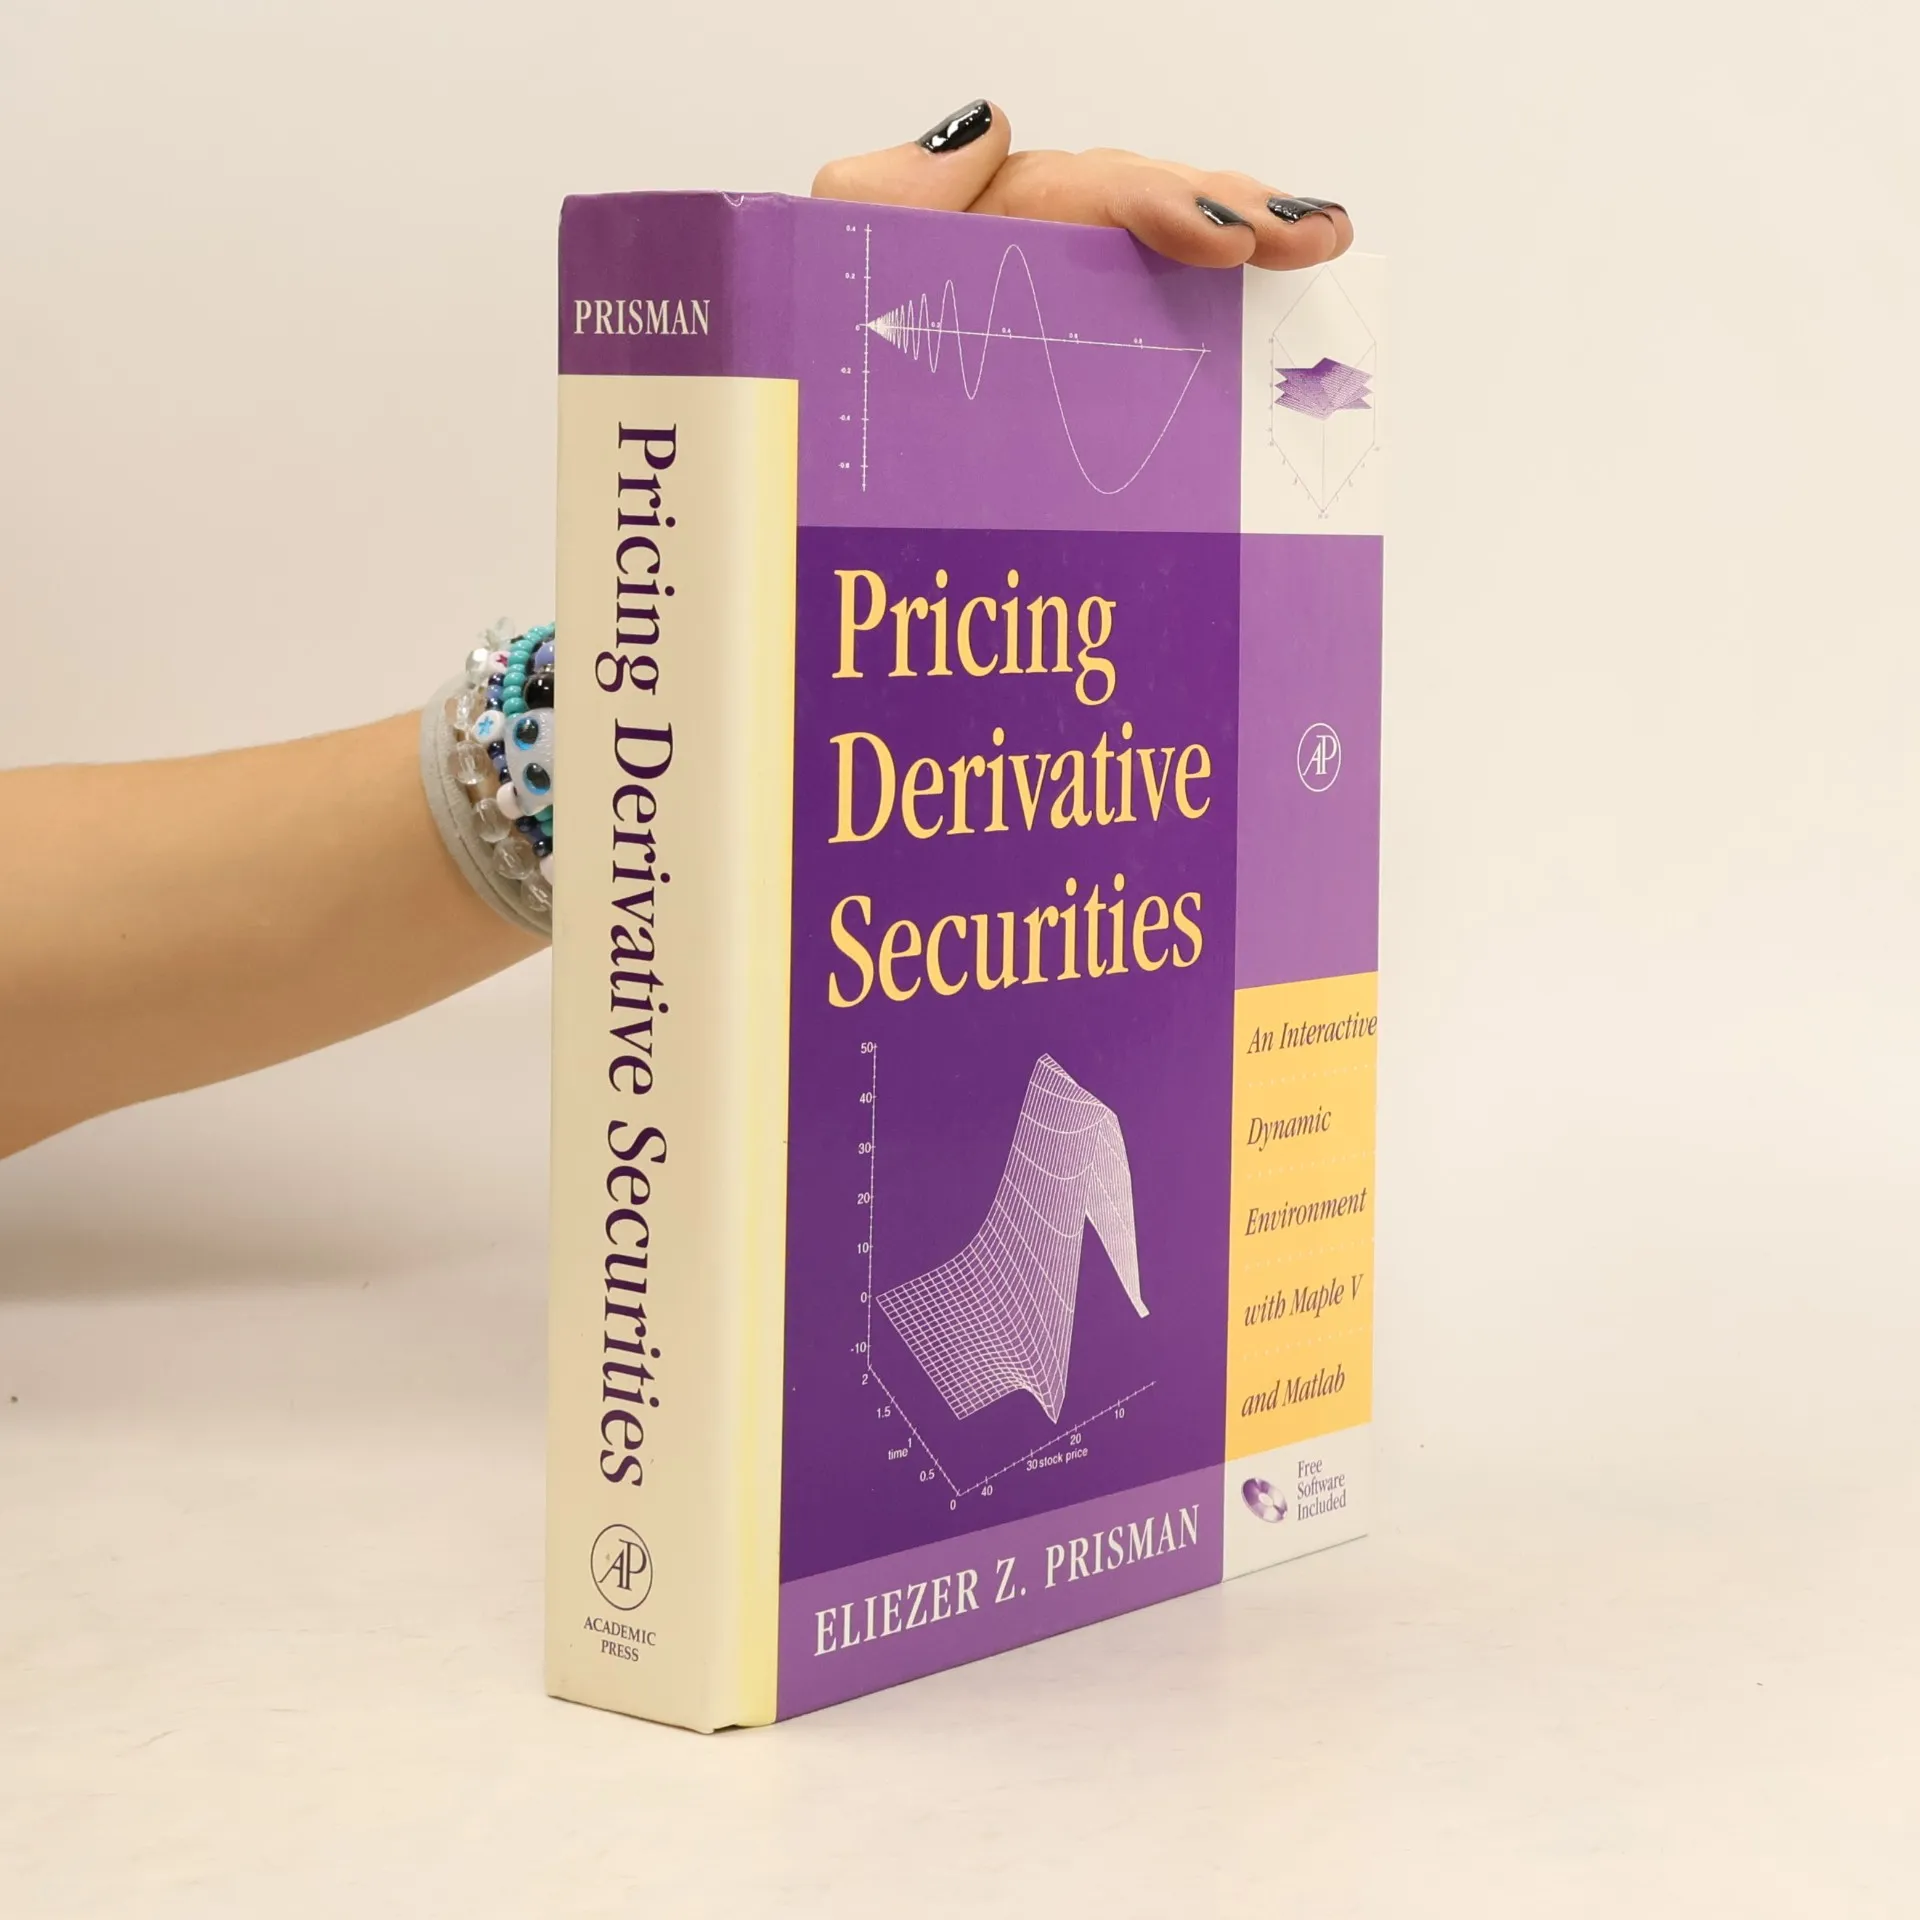
Pricing derivatives theory comes alive in this self-contained interactive experience in financial pricing. The no-arbitrage perspective in a one-period state-preference model drives the book, and the Maple® and Matlab® programs help readers visualize payoffs and respond to various constraints and conditions. With clear explanations and lavish illustrations, Pricing Derivative An Interactive, Dynamic Environment with Maple V and Matlab teaches the core theoretical concepts so often disguised behind difficult terms and institutional details.Readers can experiment with the electronic packages forever, using the book and its solutions manual as a tutorial that can help solve problems of increasing complexity.Key Features* Enclosed CD-ROM includes the student version of Maple V; it provides an interactive, dynamic and friendly environment allowing students to learn through hands on experience* Enhances learning by altering the commands in the on-line files, varying them at will, in order to experiment with applications of the concepts and different (reader-generated) examples, in addition to the ones already in the prepared file* Provides both the framework and the tools, based on the no free lunch concept, by which readers can analyze and appreciate different scenarios, including those that are not covered in the book, related to derivative securities* Basic concepts of stochastic calculus are enriched with demonstrations using animation, simulation and three-dimensional graphs thereby overcoming mathematical complexity * The MATLAB® Graphic User Interface provides the ability to bring to life on the screen the theoretical material of the chapters
Compra de libros
Pricing Derivative Securities, Eliezer Z. Prisman
- Idioma

- Publicado en
- 2000
- Encuadernación
- (Tapa dura),
- Estado del libro
- Dañado
- Precio
- 15,99 €
Métodos de pago
Nadie lo ha calificado todavía.
- Título
- Pricing Derivative Securities
- Subtítulo
- An Interactive, Dynamic Environment with Maple V and Matlab - Free Software Included
- Idioma
- Inglés
- Autores
- Eliezer Z. Prisman
- Editorial
- Academic press
- Publicado en
- 2000
- Formato
- Tapa dura
- Páginas
- 756
- ISBN10
- 0125649150
- ISBN13
- 9780125649155
- Serie
- Categorías
- Etiquetas
- Comercio, Finanzas, Banca, Procesamiento de datos, Microeconomía
- Descripción
- Pricing derivatives theory comes alive in this self-contained interactive experience in financial pricing. The no-arbitrage perspective in a one-period state-preference model drives the book, and the Maple® and Matlab® programs help readers visualize payoffs and respond to various constraints and conditions. With clear explanations and lavish illustrations, Pricing Derivative An Interactive, Dynamic Environment with Maple V and Matlab teaches the core theoretical concepts so often disguised behind difficult terms and institutional details.Readers can experiment with the electronic packages forever, using the book and its solutions manual as a tutorial that can help solve problems of increasing complexity.Key Features* Enclosed CD-ROM includes the student version of Maple V; it provides an interactive, dynamic and friendly environment allowing students to learn through hands on experience* Enhances learning by altering the commands in the on-line files, varying them at will, in order to experiment with applications of the concepts and different (reader-generated) examples, in addition to the ones already in the prepared file* Provides both the framework and the tools, based on the no free lunch concept, by which readers can analyze and appreciate different scenarios, including those that are not covered in the book, related to derivative securities* Basic concepts of stochastic calculus are enriched with demonstrations using animation, simulation and three-dimensional graphs thereby overcoming mathematical complexity * The MATLAB® Graphic User Interface provides the ability to bring to life on the screen the theoretical material of the chapters