

Más información sobre el libro
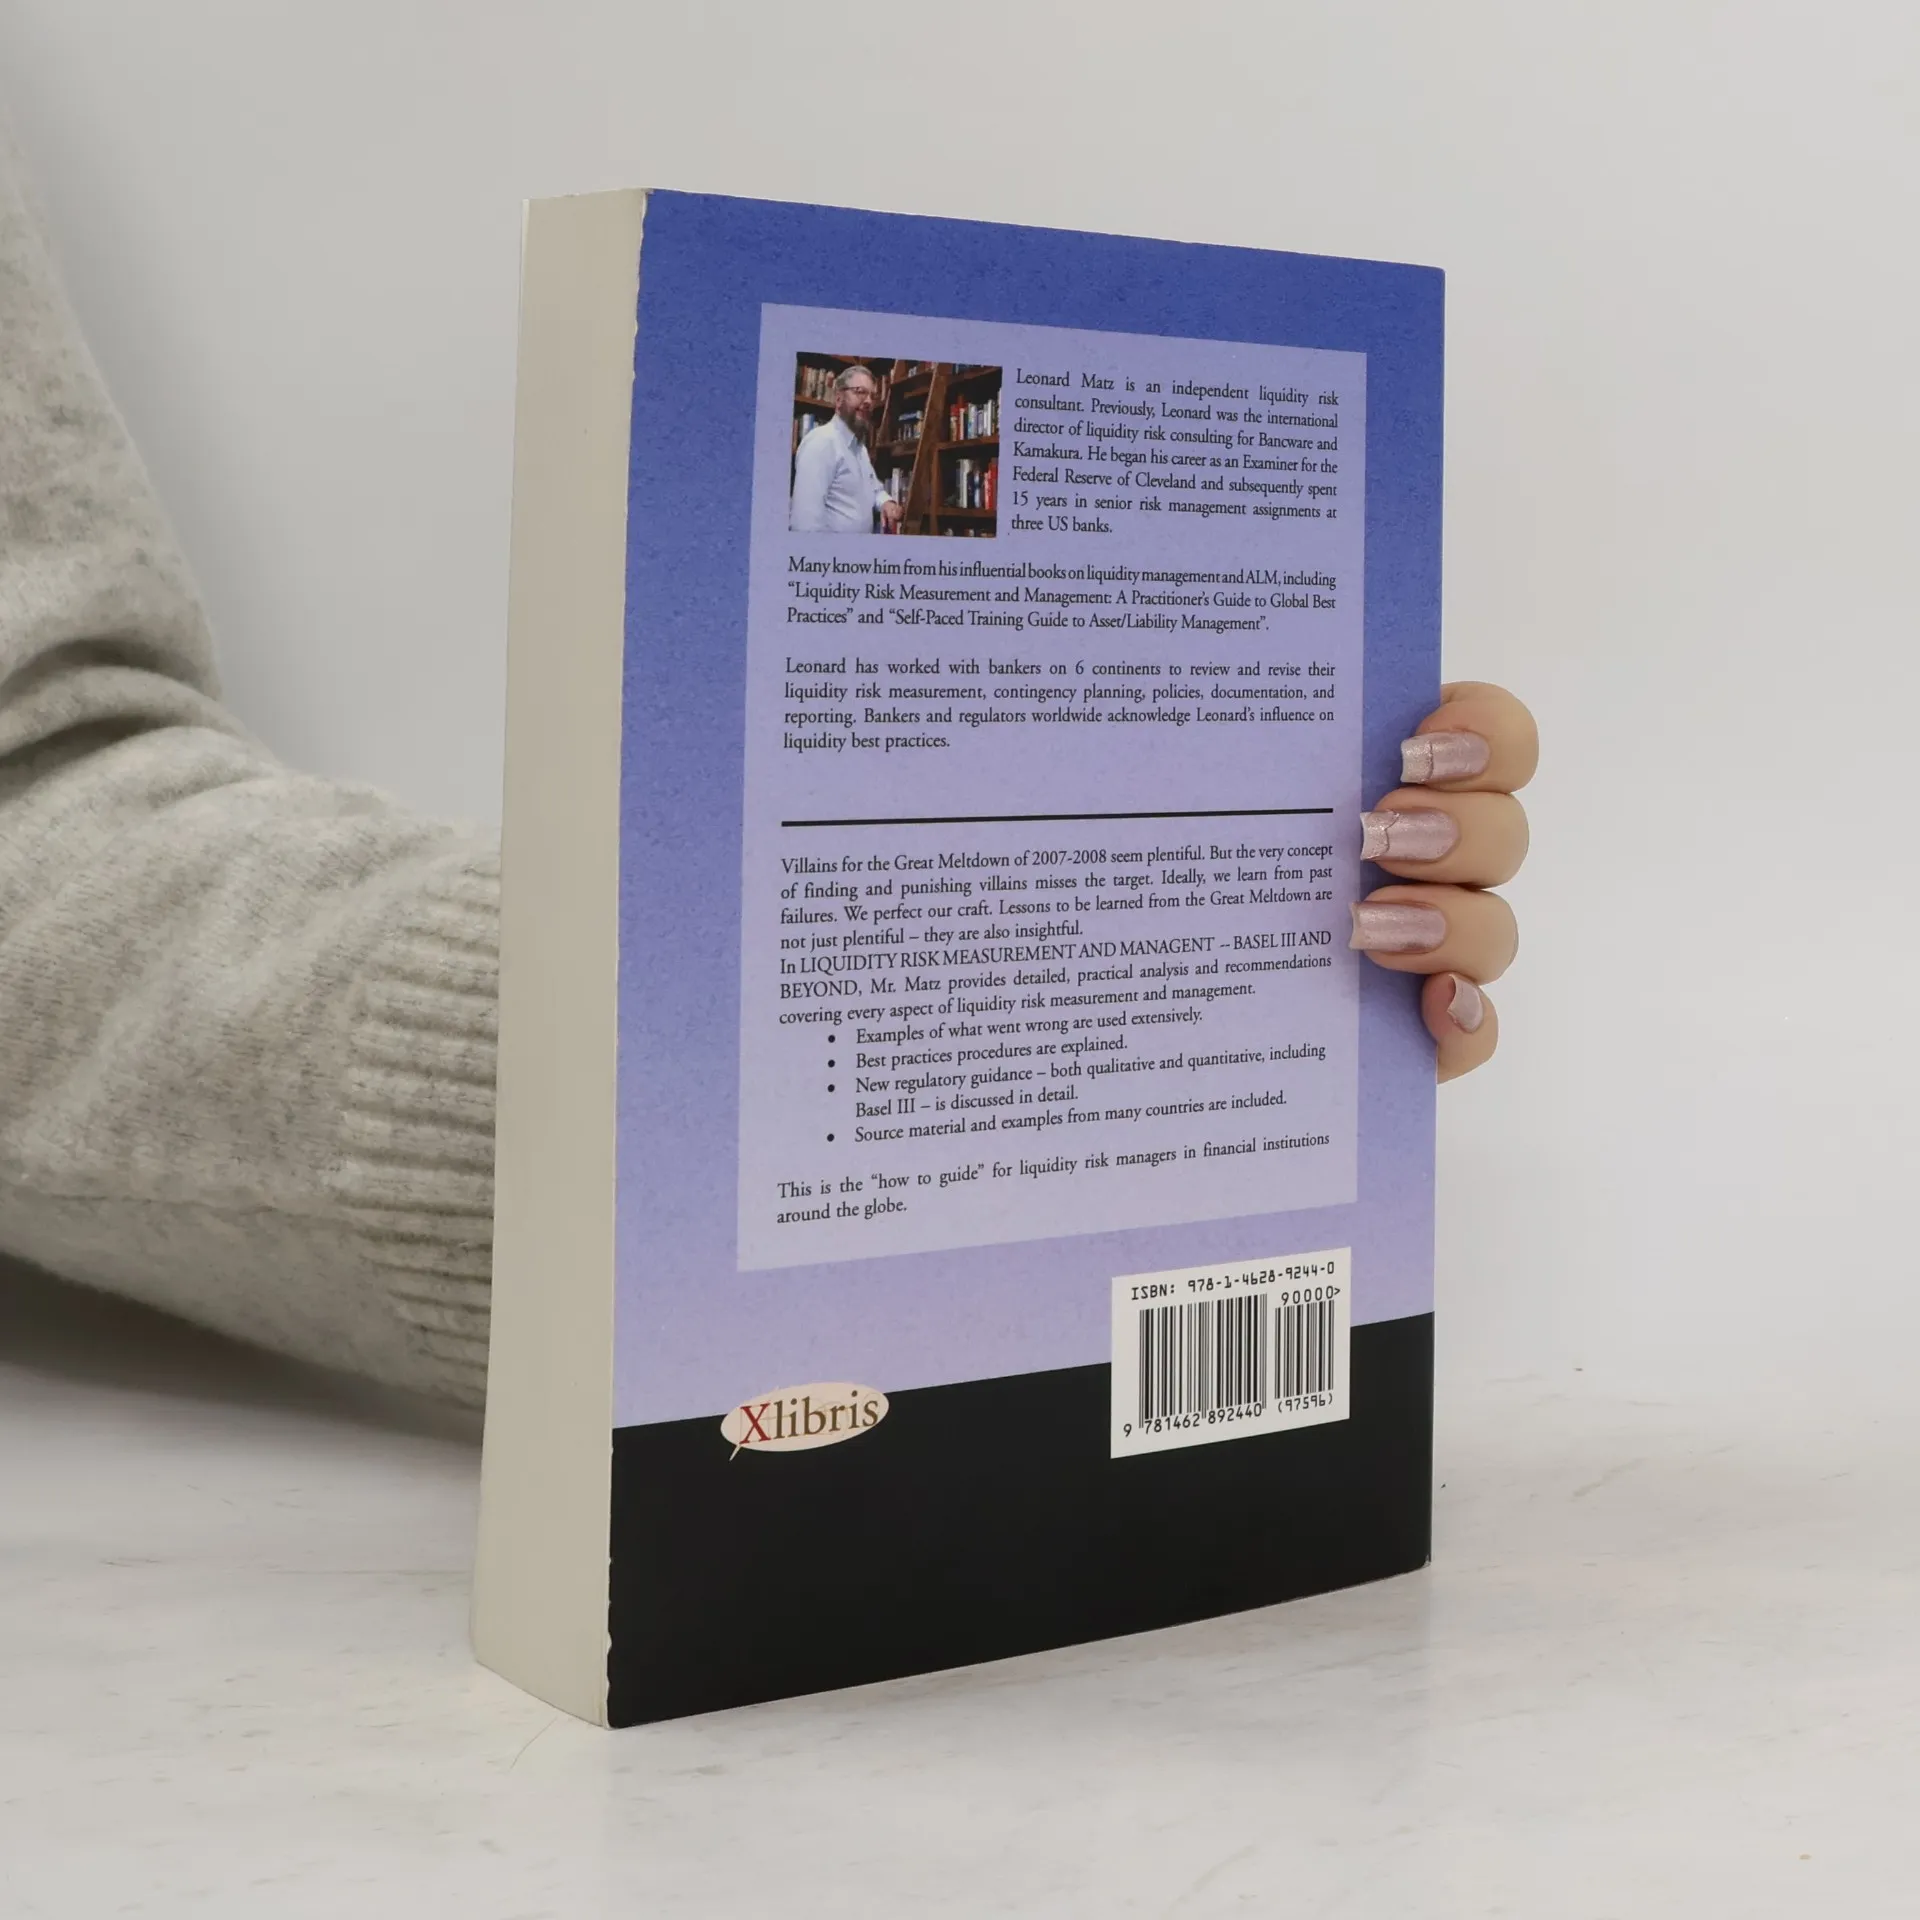
Villains for the Great Meltdown of 2007-2008 seem plentiful. But the very concept of finding and punishing villains misses the target. Ideally, we learn from past failures. We perfect our craft. Lessons to be learned from the Great Meltdown are not just plentiful they are also insightful. In LIQUIDITY RISK MEASUREMENT AND MANAGENT -- BASEL III AND BEYOND, Mr. Matz provides detailed, practical analysis and recommendations covering every aspect of liquidity risk measurement and management. Examples of what went wrong are used extensively. Best practices procedures are explained. New regulatory guidance both qualitative and quantitative, including Basel III is discussed in detail. Source material and examples from many countries are included. This is the "how to guide" for liquidity risk managers in financial institutions around the globe.
Compra de libros
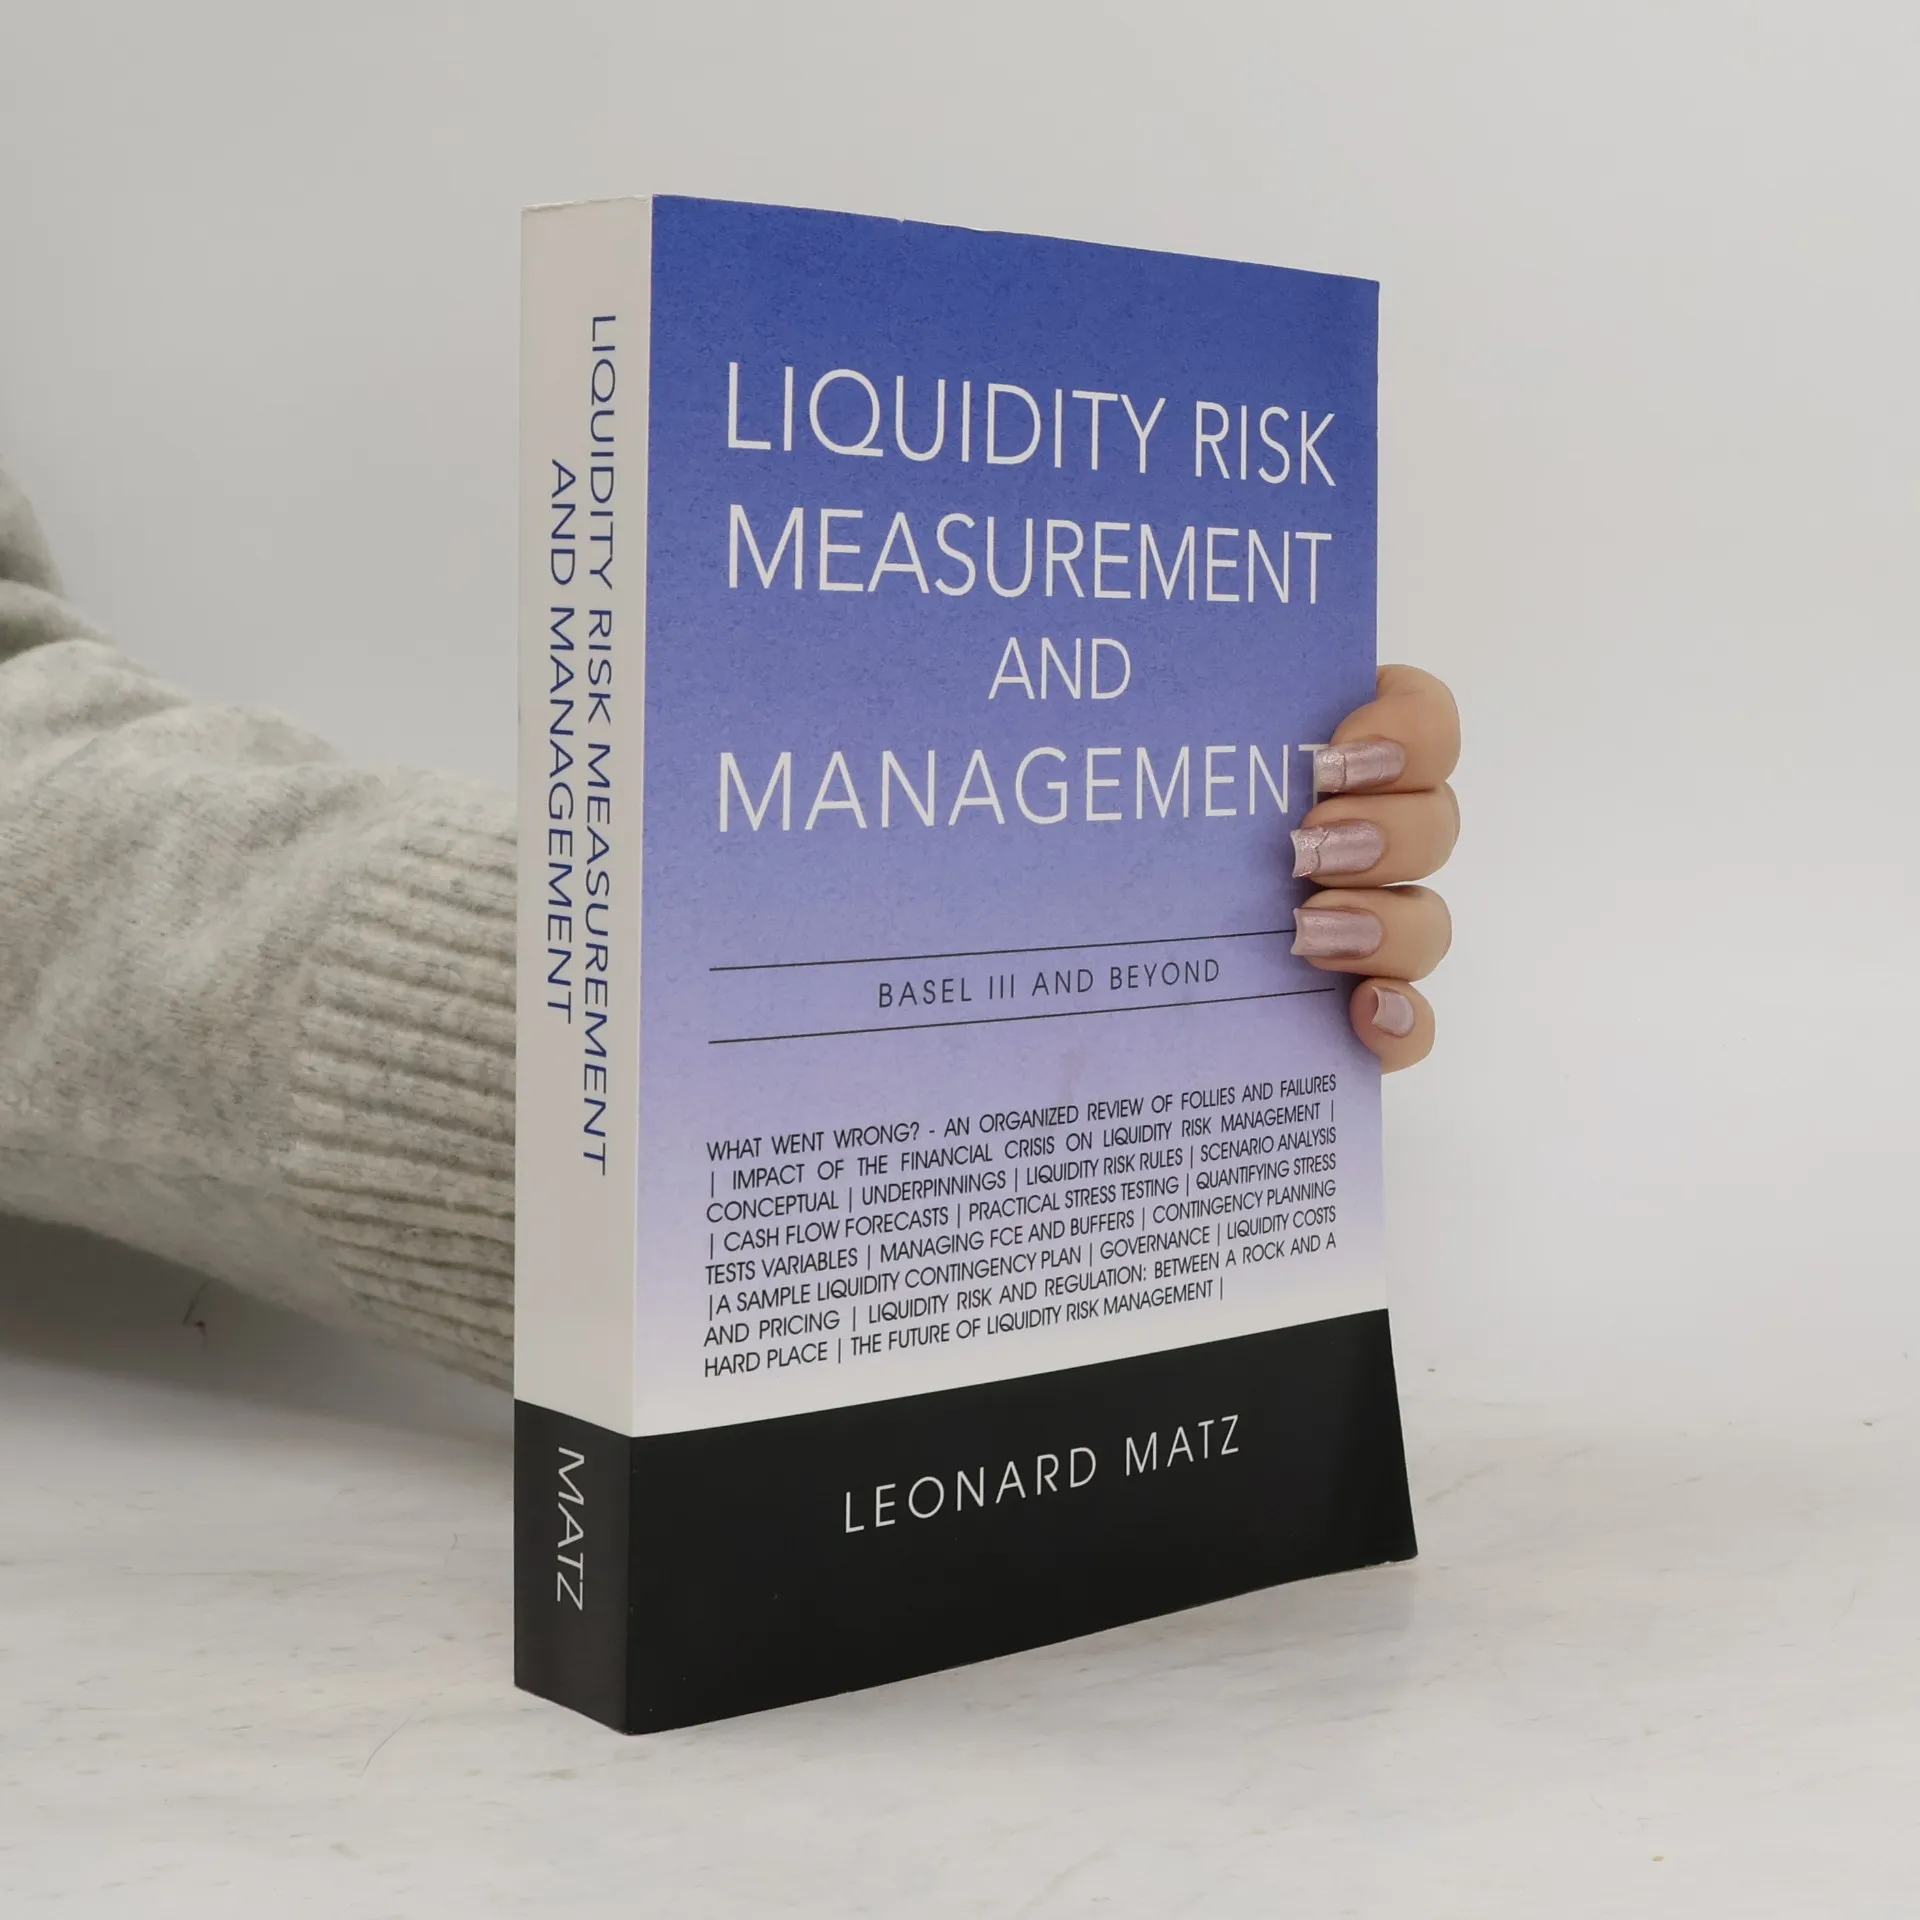
Liquidity Risk Measurement and Management, Leonard Matz
- Idioma

- Publicado en
- 2011
- Encuadernación
- (Tapa blanda),
- Estado del libro
- Bueno
- Precio
- 7,79 €
Métodos de pago
Nadie lo ha calificado todavía.
- Título
- Liquidity Risk Measurement and Management
- Subtítulo
- Base L III And Beyond
- Idioma
- Inglés
- Autores
- Leonard Matz
- Editorial
- Xlibris
- Publicado en
- 2011
- Formato
- Tapa blanda
- Páginas
- 616
- ISBN10
- 1462892442
- ISBN13
- 9781462892440
- Serie
- Categorías
- Etiquetas
- Comercio, Teorías científicas, Banca, Microeconomía
- Descripción
- Villains for the Great Meltdown of 2007-2008 seem plentiful. But the very concept of finding and punishing villains misses the target. Ideally, we learn from past failures. We perfect our craft. Lessons to be learned from the Great Meltdown are not just plentiful they are also insightful. In LIQUIDITY RISK MEASUREMENT AND MANAGENT -- BASEL III AND BEYOND, Mr. Matz provides detailed, practical analysis and recommendations covering every aspect of liquidity risk measurement and management. Examples of what went wrong are used extensively. Best practices procedures are explained. New regulatory guidance both qualitative and quantitative, including Basel III is discussed in detail. Source material and examples from many countries are included. This is the "how to guide" for liquidity risk managers in financial institutions around the globe.