

¡Agotado, pero muy deseado!
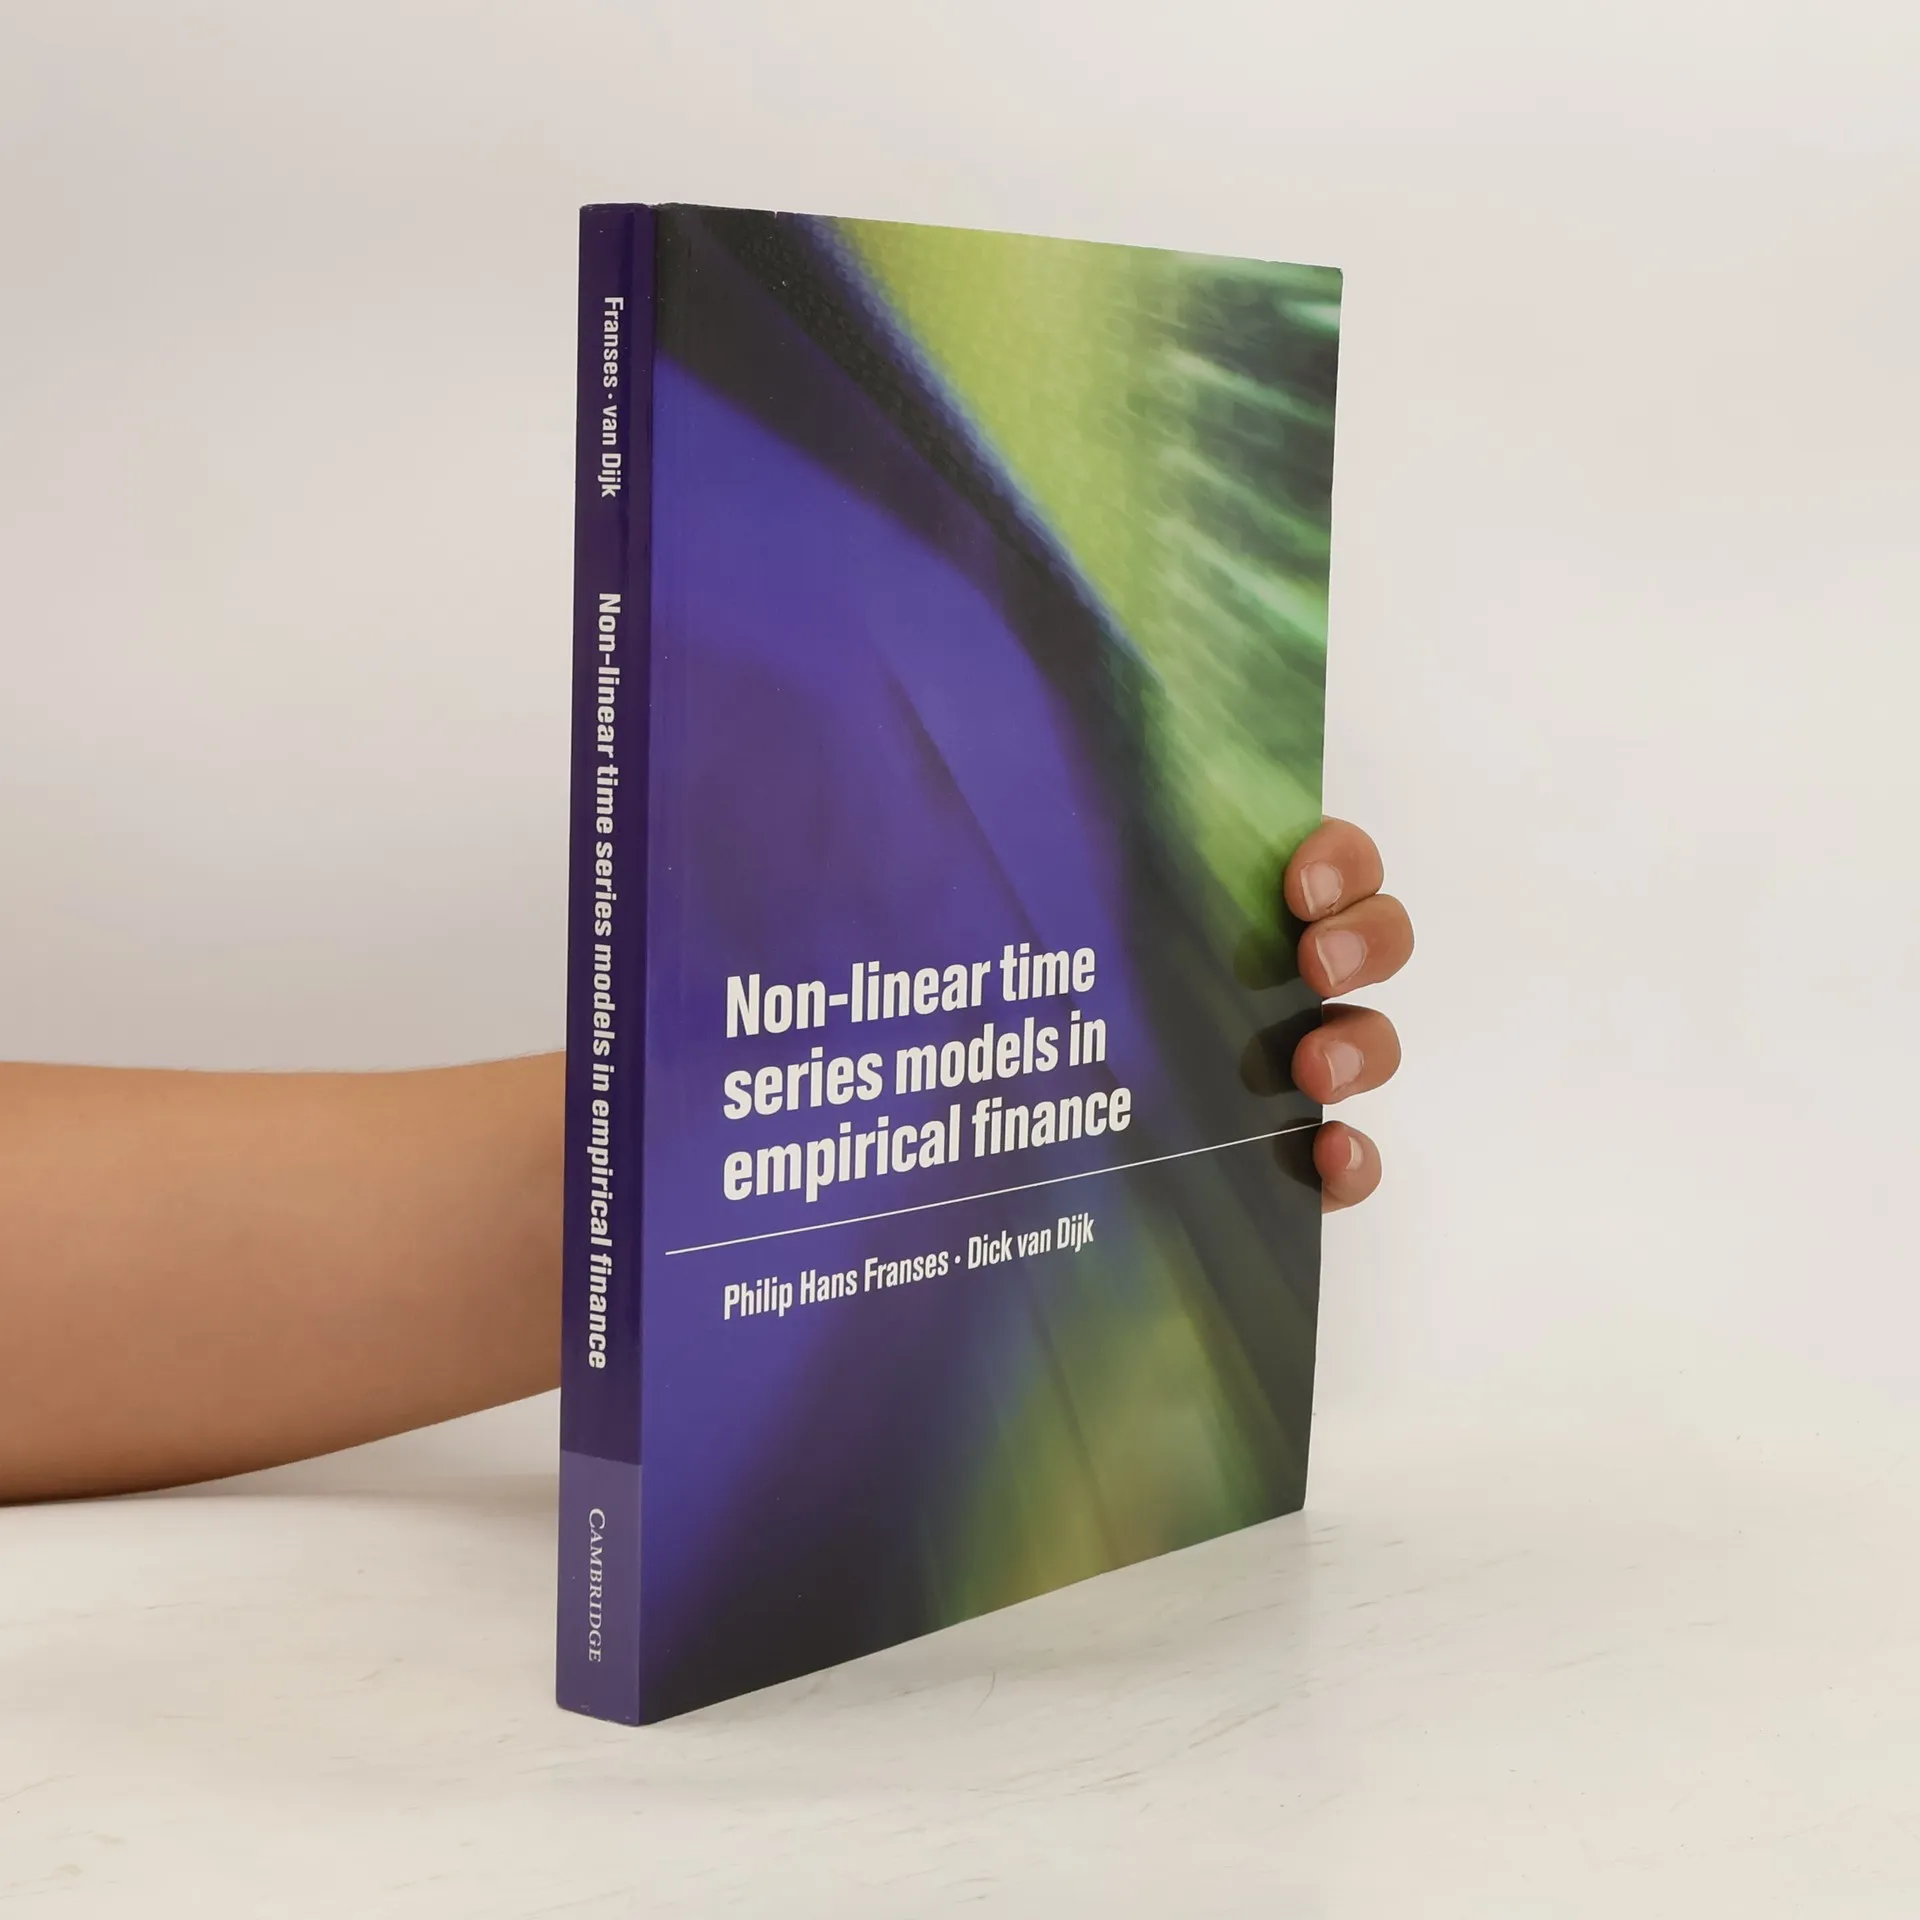
Más información sobre el libro
This is the most up-to-date and accessible guide to one of the fastest growing areas in financial analysis by two of the most accomplished young econometricians in Europe. This classroom-tested advanced undergraduate and graduate textbook provides an in-depth treatment of recently developed nonlinear models, including regime-switching and artificial neural networks, and applies them to describing and forecasting financial asset returns and volatility. It uses a wide range of financial data, drawn from sources including the markets of Tokyo, London and Frankfurt.
Compra de libros
Non-Linear Time Series Models in Empirical Finance, Philip Hans Franses, Dick van Dijk
- Idioma

- Publicado en
- 2000
- Encuadernación
- (Encuadernación flexible)
Te avisaremos por correo electrónico en cuanto lo localicemos.
Métodos de pago
Nos falta tu reseña aquí
- Título
- Non-Linear Time Series Models in Empirical Finance
- Idioma
- Inglés
- Autores
- Philip Hans Franses, Dick van Dijk
- Editorial
- Cambridge University Press
- Publicado en
- 2000
- Formato
- Encuadernación flexible
- Páginas
- 296
- ISBN10
- 0521779650
- ISBN13
- 9780521779654
- Serie
- Categorías
- Etiquetas
- Comercio
- Calificación
- 3,65 de 5
- Descripción
- This is the most up-to-date and accessible guide to one of the fastest growing areas in financial analysis by two of the most accomplished young econometricians in Europe. This classroom-tested advanced undergraduate and graduate textbook provides an in-depth treatment of recently developed nonlinear models, including regime-switching and artificial neural networks, and applies them to describing and forecasting financial asset returns and volatility. It uses a wide range of financial data, drawn from sources including the markets of Tokyo, London and Frankfurt.